

In Focus: Two Digital Currencies, One Big Difference
India is one of the largest digital economies in the world, with its digital ecosystem now valued at nearly $400 billion, according to a 2025 report by the Ministry of Electronics and Information Technology (MeitY) and the Ministry of Statistics and Programme Implementation (MoSPI). Rapid digitalisation, widespread smartphone adoption, affordable internet access, and government-led Digital Public Infrastructure (DPI) initiatives have fundamentally transformed the way Indians transact, save, invest, and access financial services.
This transformation is perhaps best reflected in the phenomenal growth of the Unified Payments Interface (UPI). In June 2026, UPI transactions reached a record ₹28.9 lakh crore, further cementing its position as the backbone of India’s digital payments ecosystem. From street vendors and neighbourhood grocery stores to e-commerce platforms and large corporations, UPI has become an integral part of everyday life. Beyond convenience, it has significantly expanded financial inclusion by bringing millions of previously underserved individuals into the formal financial system while steadily reducing the country’s dependence on cash.
However, the rapid expansion of digital finance has also introduced a new set of challenges. As highlighted in Aakhya Weekly #192, the Reserve Bank of India (RBI) has been preparing a series of measures to combat the growing incidence of digital fraud, identity theft, mule accounts, and money laundering facilitated through digital payment channels. Protecting consumers and preserving trust in India’s rapidly evolving digital financial ecosystem have consequently become central priorities for regulators.
The RBI’s concerns, however, are no longer limited to conventional digital payment systems. As investments in Virtual Digital Assets (VDAs), including cryptocurrencies, continue to grow despite an evolving regulatory landscape, the central bank has increasingly shifted its attention towards strengthening oversight of this emerging sector. Its objective is not merely to regulate a new asset class, but to improve transparency, curb illicit financial flows, and ensure that digital financial innovation develops within a secure and accountable framework.
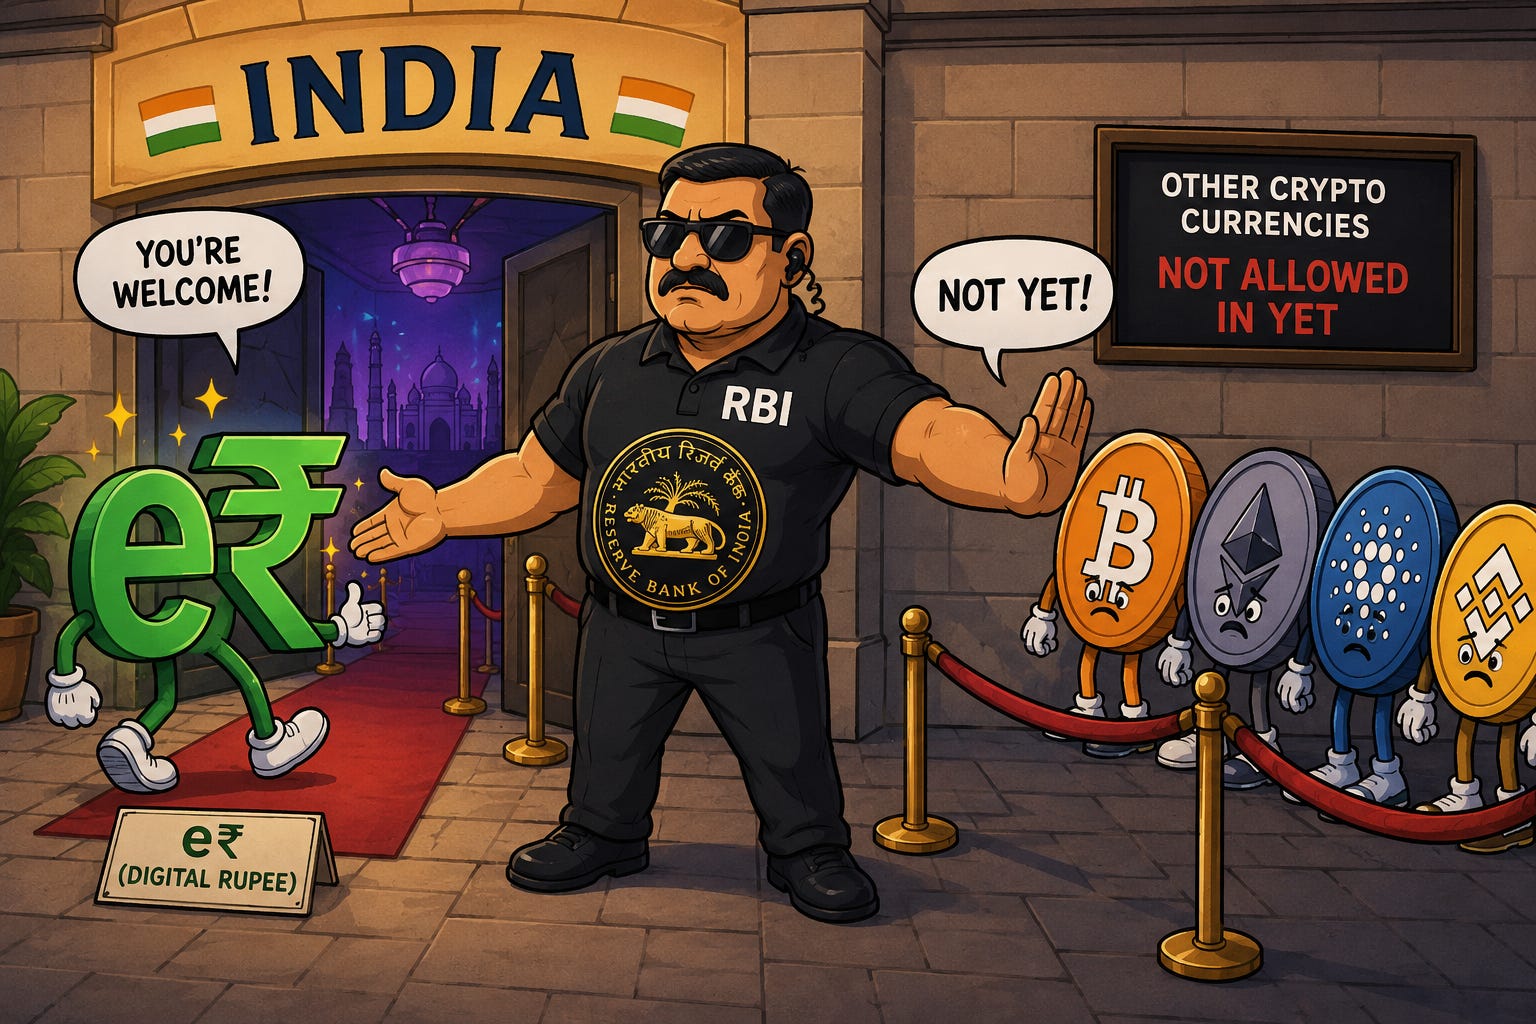
It was against this backdrop that, during a Parliamentary panel meeting in early July, the RBI once again reiterated its opposition to the legalisation of private Virtual Digital Assets (VDAs) such as Bitcoin and Ethereum. The position immediately reignited a familiar question: if the RBI itself is actively promoting a digital currency, why does it continue to oppose cryptocurrencies?
The answer lies in a simple but often overlooked distinction. While both the Digital Rupee and cryptocurrencies exist in digital form, they serve fundamentally different purposes and are built on entirely different principles of issuance, governance, and accountability.
The Digital Rupee: A Sovereign Digital Currency
The Digital Rupee, or e₹, is India’s Central Bank Digital Currency (CBDC) a digital version of the Indian rupee issued directly by the Reserve Bank of India as legal tender. Introduced in 2022, the e₹ carries exactly the same value and legal status as a physical banknote. The only difference is its form. Since every Digital Rupee is issued by the RBI, it represents a direct liability of the central bank and enjoys the same sovereign backing and public trust as traditional currency.
Over the past few years, the RBI has gradually expanded the scope of its CBDC pilots beyond simple retail payments. During FY 2025–26, it also launched welfare-linked Digital Rupee pilots across several states, allowing beneficiaries to receive food subsidies through the e₹ under the Public Distribution System (PDS). Unlike conventional cash transfers, these digital tokens were programmable and could only be spent at designated ration shops. This ensured that government subsidies were used exclusively for their intended purpose while reducing leakages, improving transparency, and strengthening the efficiency of Direct Benefit Transfers (DBTs). These pilots also demonstrated how a sovereign digital currency can be designed not merely as a payment instrument, but as a policy tool capable of improving public service delivery.
Digital Rupee vs Cryptocurrencies: What’s the Difference?
It is through this broader perspective that the differences between the Digital Rupee and cryptocurrencies become much clearer.
The most fundamental distinction lies in who issues the currency. The Digital Rupee is sovereign money, created and fully backed by the Reserve Bank of India. Functionally, it is equivalent to a digital banknote and represents a direct claim on the central bank. Cryptocurrencies such as Bitcoin and Ethereum, by contrast, are privately created digital assets operating on decentralised blockchain networks. They have no central issuer, no sovereign backing, and no institution guaranteeing their value. Instead, their prices are determined entirely by market demand and supply.
This difference in issuance naturally extends to price stability. One Digital Rupee will always remain equal to one physical rupee. Its purchasing power does not fluctuate independently because it is simply another representation of India’s national currency. Cryptocurrencies, on the other hand, are highly volatile. Their prices can rise or fall dramatically within hours, influenced by speculation, investor sentiment, macroeconomic developments, regulatory announcements, technological events, or even social media activity. Such volatility may make them attractive as speculative investment assets for some investors, but it significantly limits their effectiveness as a stable medium of exchange for everyday transactions.
The RBI also views the issue through the lens of monetary sovereignty. Since the Digital Rupee is issued and managed by the central bank, the RBI retains complete control over its supply and circulation. This allows it to implement monetary policy, manage liquidity, maintain financial stability, and preserve confidence in India’s monetary system. Decentralised cryptocurrencies, by design, operate independently of any central authority. If they were to become widely accepted as a means of payment, they could gradually reduce the effectiveness of monetary policy by shifting economic activity outside the central banking system and weakening the RBI’s ability to influence financial conditions.
Financial integrity represents another major area of distinction. Transactions involving the Digital Rupee take place within India’s regulated financial infrastructure and remain subject to the country’s legal and regulatory framework. This enables authorities to implement Know Your Customer (KYC) requirements, monitor suspicious transactions, combat fraud, and strengthen compliance with anti-money laundering regulations.
The RBI has consistently argued that certain private virtual digital assets, particularly those facilitating pseudonymous or cross-border transactions, can be exploited for illicit activities such as money laundering, terror financing, narcotics trafficking, tax evasion, and other forms of financial crime. While blockchain technology itself offers transparency, the global and decentralised nature of many cryptocurrency ecosystems can make regulatory enforcement considerably more challenging than within traditional financial systems.
These concerns have become increasingly relevant as cryptocurrency adoption continues to expand worldwide. Although India has introduced taxation and reporting requirements for VDAs, the broader regulatory framework remains under development. The RBI has therefore continued to advocate a cautious approach, emphasising that technological innovation should not come at the cost of financial stability or consumer protection.
Innovation Needs Trust, Not Just Technology
At first glance, it may appear contradictory for the RBI to champion one digital currency while opposing another. In reality, the distinction has never been about whether money is digital. Rather, it is about who issues it, who regulates it, who guarantees its value, and who remains accountable for maintaining public confidence in the financial system.
As India enters the next phase of its digital transformation, these questions are likely to become even more important. Digital finance is evolving rapidly, bringing with it new opportunities for efficiency, financial inclusion, and innovation, alongside new risks that require equally sophisticated regulatory responses. The future of India’s digital economy will therefore depend not only on embracing technological innovation, but also on striking the right balance between innovation, trust, consumer protection, and effective regulatory oversight.
Top Stories of the Week
Karnataka Targets 500 New GCCs and 3.5 Lakh Jobs by 2029 to Strengthen Digital Economy
Karnataka has unveiled an ambitious roadmap to attract 500 new Global Capability Centres (GCCs), generate 3.5 lakh jobs, and create $50 billion in economic output by 2029. Announced at the Katalyst Connect industry event, the strategy focuses on expanding the state’s GCC ecosystem beyond Bengaluru into Tier 2 and Tier 3 cities through improved infrastructure, policy incentives, and lower operational costs. The government also plans to strengthen industry collaboration, enhance talent development, and position Karnataka as a global hub for engineering, research, and innovation, reinforcing its leadership in India’s digital economy.
Uttar Pradesh Approves Data Centre Policy 2026 to Boost AI and Digital Infrastructure
The Uttar Pradesh Cabinet has approved the Data Centre Policy 2026 with the objective of positioning the state as a leading destination for green and AI ready data centres. The policy targets investments of more than ₹2 lakh crore and aims to create an additional 2 GW of data centre capacity to support the growing demand for cloud computing, AI and digital services.
Replacing the state’s 2021 policy, it introduces enhanced incentives for AI focused, GPU based and energy efficient facilities. The policy is expected to strengthen Uttar Pradesh’s digital infrastructure, attract technology investments and generate employment while reinforcing the state’s ambition to become a globally competitive digital economy hub.
A Few Good Reads
C. Raja Mohan asserts that a “G Minus Two” framework can help Asia navigate the evolving US-China equation.
Dani Rodrik argues that the Trump administration’s tariff policy is an extractive use of US economic power that is ultimately self-defeating, inviting retaliation while undermining America’s global credibility and leadership.
M. Govinda Rao highlights that Karnataka’s development story remains incomplete without balanced regional growth and better human development.
Vinay Sarawagi notes that governments are becoming strategic investors, and India should not ignore the opportunity to back its own technology champions.
P. Alli highlights that India’s recurring floods and water shortages reflect a failure to manage water efficiently across seasons and regions, rather than a lack of water itself.